All Categories
Featured
Table of Contents
Dangers are tilted to the drawback. In case of a prolonged conflict, the present impacts on the region will be compoundedthrough raised energy and food costs, declining trade, tourism and remittances, increased fiscal pressures, and displacement. "The existing crisis is a stark tip of the work ahead for the area: not just to weather shocks, but to reconstruct more resilient economies with more powerful macroeconomic fundamentals, innovate and improve governance, buy facilities, and enhance employment-creating sectors," stated.
With peace and the best action, nations can construct the organizations, capabilities and competitive sectors that create chances for people." With this long-term vision in mind, the report takes a close look at the area's capacity for industrial policy government actions to increase tactical service activity as a motorist of economic growth and job production.
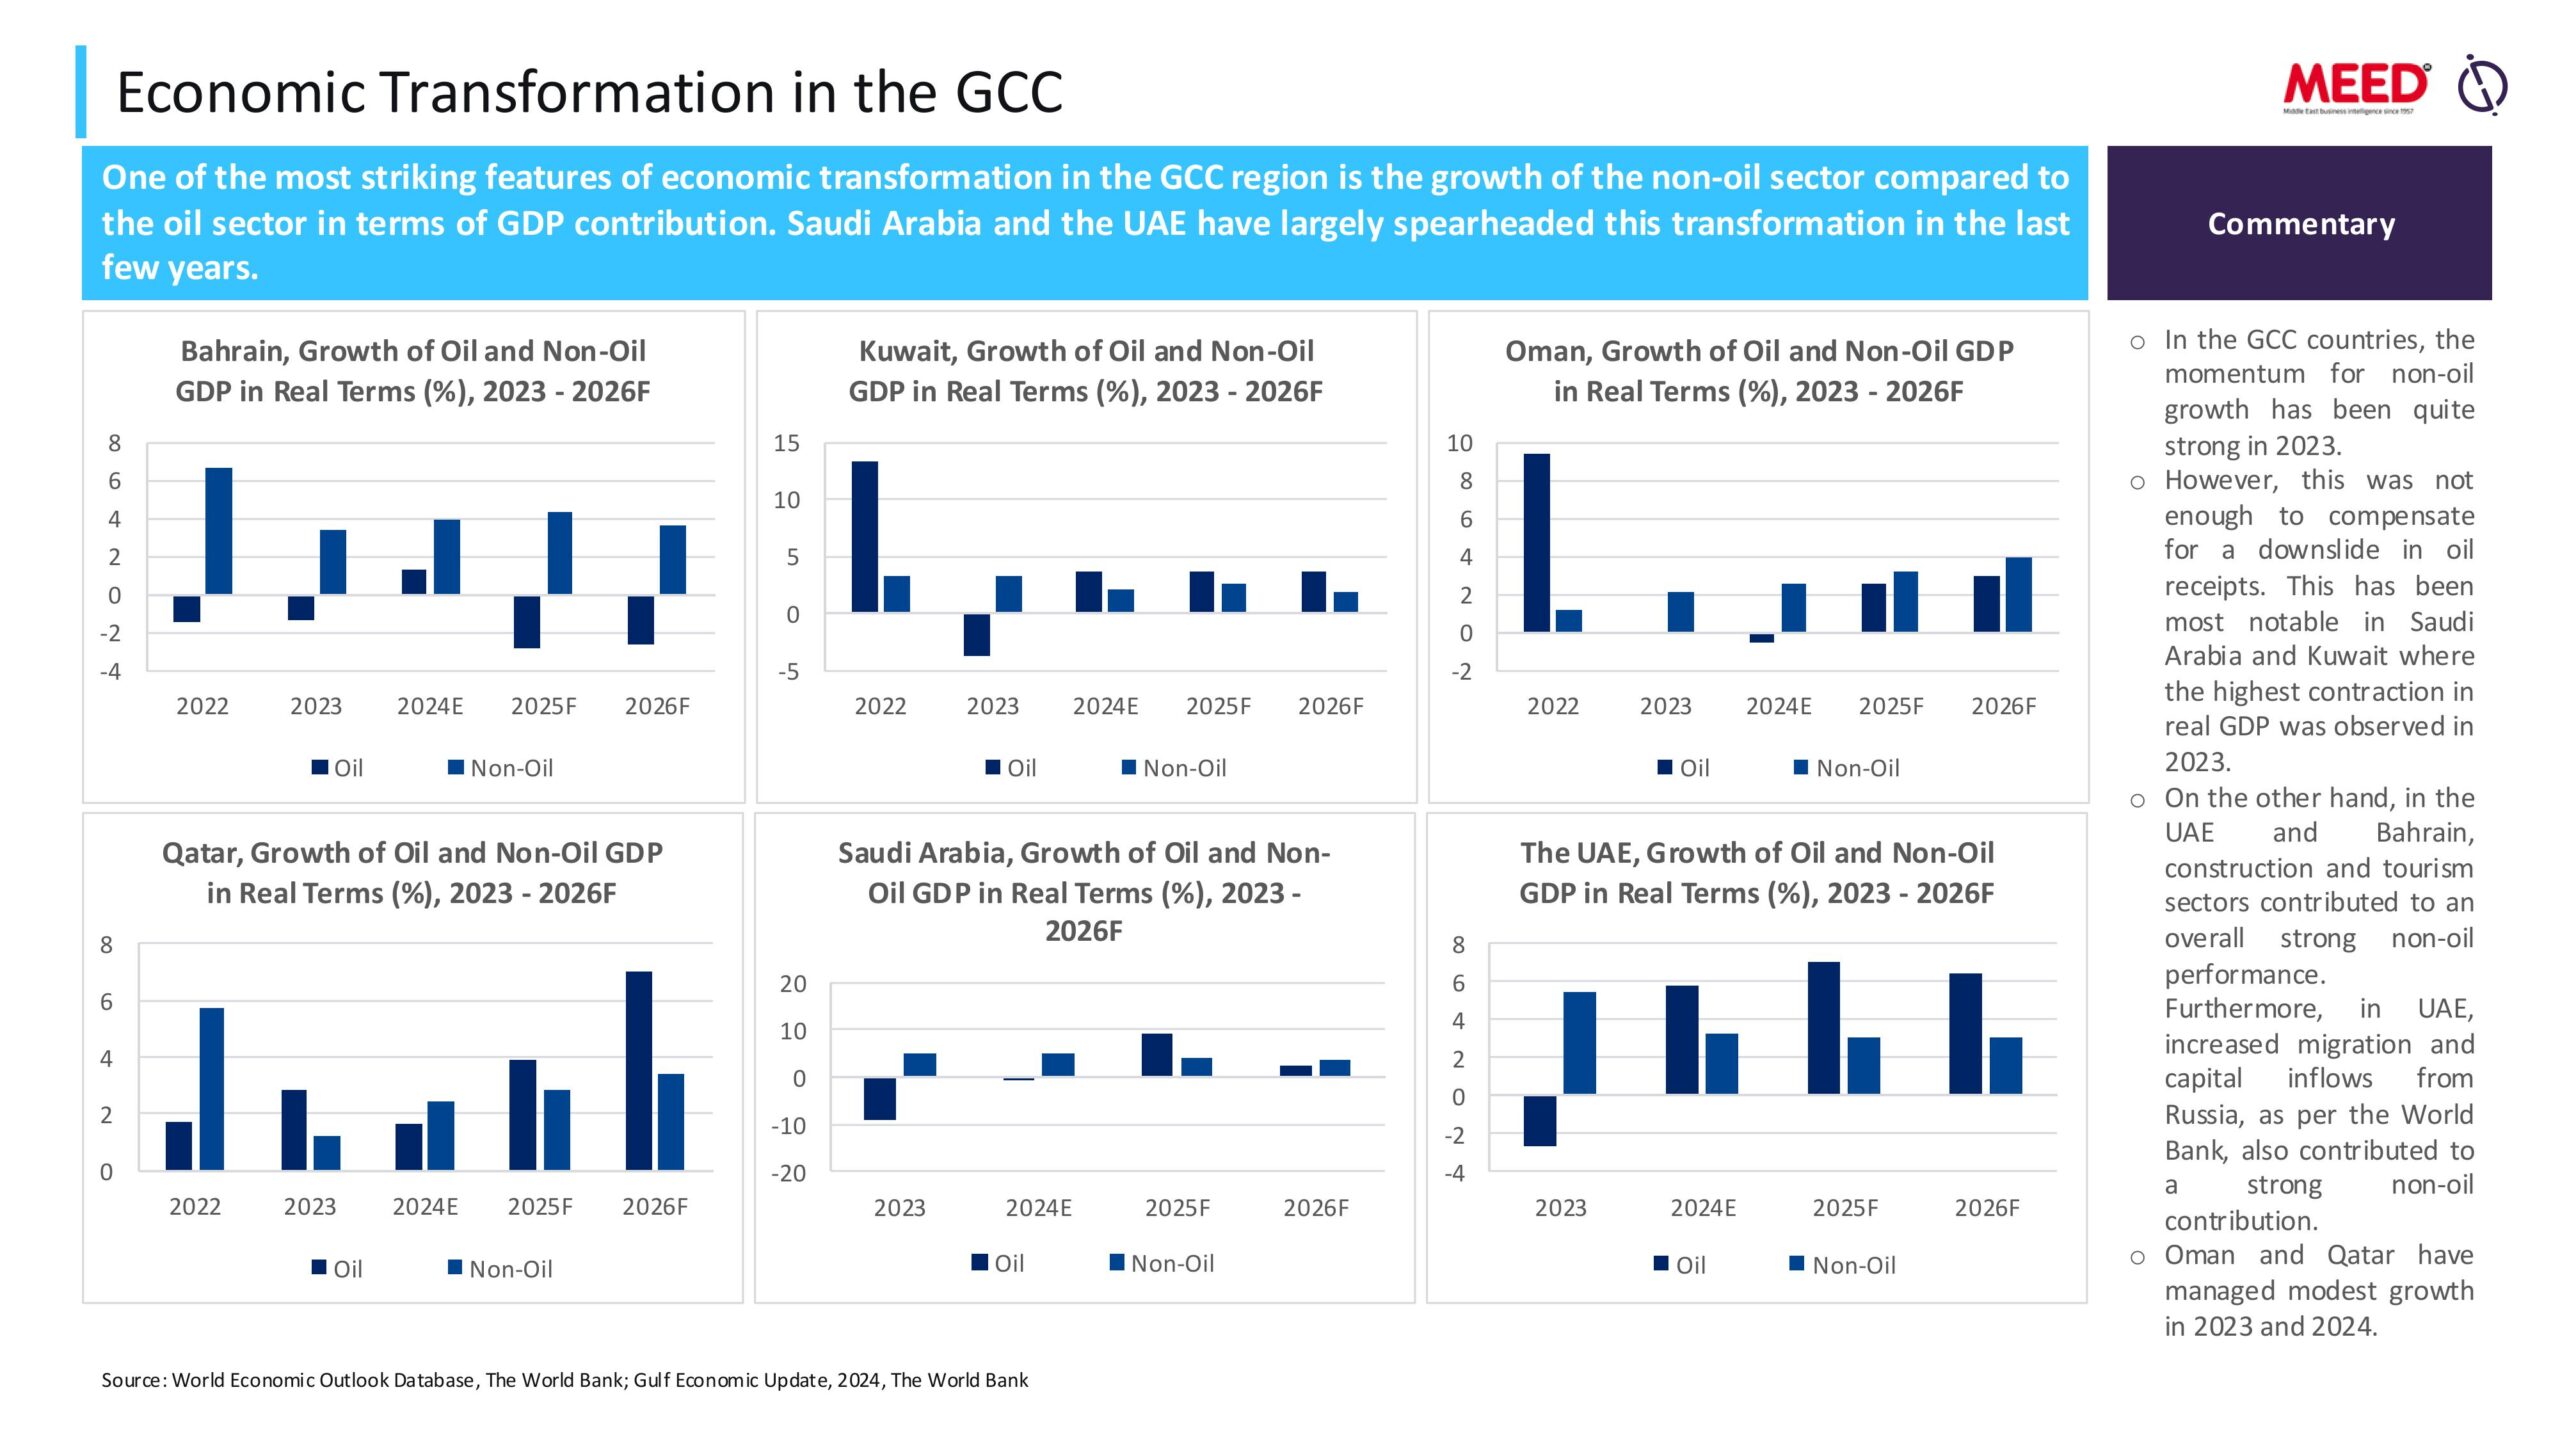
Federal governments in the area have actually adopted industrial policy at a high rate in the last decade, frequently through sovereign wealth funds and state-owned business, however the results have actually been blended. The report highlights the critical need for strong institutions and cautious targeting of policies. "As countries deal with the heavy toll of today conflict, it is essential to also not forget the work required for lasting peace and success," said.
Mastering Capital Strategies for a 2026 Economy
Q2 2026: The ICAEW Economic Update Middle East, is a quarterly economic forecast for the region prepared directly for the financing occupation. The GCC economy faces a significant contraction this year pending information of the US-Iran arrangement to end the war. We anticipate energy flows, tourist and financier belief to slowly normalise as war disruptions go away.

The interim contract in between the US and Iran is a significant action towards reaching a full-blown deal. A complete return to normality in the Strait of Hormuz will likely take time, however the threat of a recession-inducing oil price spike has actually decreased. Global GDP is anticipated to grow by 2.4% this year, 0.2 ppt less than we projected three months earlier, and 3.1% in 2027.
Economic Climate and Capital Management for 2026We forecast a 4.1% contraction in Middle East GDP this year (versus forecasted 3.6% growth before the war), greater than the decrease in the very first year of the Covid pandemic. Kuwait, Iran, Iraq and Qatar stick out as the hardest hit, owing to their inability to avoid the interruption to regional shipping, war-driven facilities damage and tourism losses.
Benefits of Expanding Manufacturing Projects across Middle EastOur 2026 outlook for the GCC is weaker than three months ago, with GDP forecast to agreement by 2.4% compared to a 0.2% decrease forecasted previously. We expect Oman and Saudi Arabia to be the least adversely affected by the fallout from the conflict, with both economies continuing to broaden this year.
The economic damage sustained in the last couple of months is considerable. Saudi GDP data for Q1 showed growth slowed to 3% y/y, with non-oil activities broadening by 2.9%, the weakest speed because the Covid pandemic. On a seasonally changed basis, GDP contracted 1.2% q/q, driven by a 6.8% fall in oil activities as the Strait of Hormuz disruption struck late in the quarter.
The Future Investment Landscape of the GCC
Aside from Oman, all GCC producers as well as Iran and Iraq have suffered comprehensive oil and gas production losses since the start of the dispute. Might information show local production almost halved from pre-war levels, with the decline deepening relative to March and April. Rerouting efforts, including by Saudi Arabia through the East-West Pipeline and the UAE through the Habshan-Fujairah pipeline, have assisted prevent an even larger plunge in output.

However, we anticipate GCC oil sector output to contract by 14.5% this year, which will mark the steepest decline in numerous decades. We then anticipate a 23.5% rebound next year, driven mainly by normalisation from a seriously depressed base. Oil prices have actually been volatile, reducing listed below $85 per barrel as the interim contract was revealed.
In the medium term, we anticipate oil costs to be slightly lower than our pre-war standard, as the UAE's departure from OPEC+ permits for a progressive boost in its output towards the 5mn barrel per day production target as soon as trade normalises. Versus this backdrop, the UAE will accelerate the building of a new West-East pipeline that should double the capability of export through Fujairah.
The May PMI studies reported output growth reaching its greatest level in three months, driven mostly by enhanced domestic need. They stay listed below long-run averages, with weak export orders and price pressures from greater product and transportation expenses are a typical style. Overall, we anticipate a 1.1% contraction in GCC non-energy sectors this year (compared to 4.2% growth pre-war) and a gradual healing over the rest of the years.

Latest Posts
Navigating Investment Strategies in a 2026 Economy
How GCC Economic Diversification Drives 2026 Growth
Actionable Tips for Entering 2026 Foreign Investment Climates